Transparent rate quotes
Live calculator showing the fee breakdown and the offered rate against the mid-market rate before commitment.
AI-Built Wise Clone
An AI-first build of every remittance mechanic: fraud signals on every transfer, corridor risk scoring that keeps payouts predictable, and personalization that grows sender lifetime value. Four synced panels ship white-label with 100% source code, on an audit-ready ledger. The almost-ready AI build goes live in 6 working days; a custom build takes 3 to 4 weeks.
Launch-ready from
$12,999
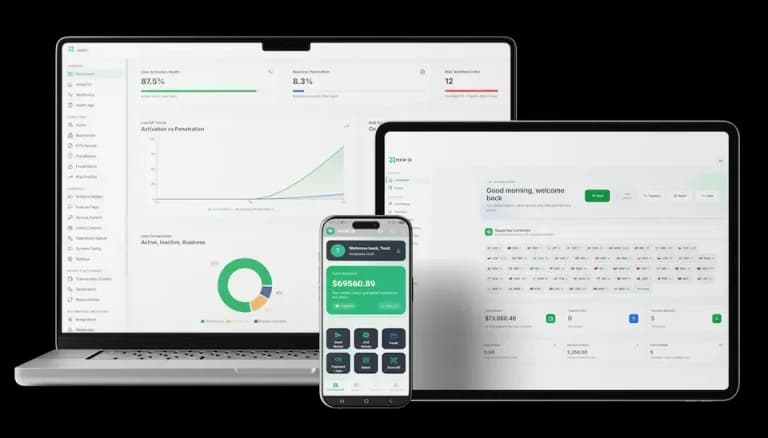
Synced panels
Almost-ready AI launch
Custom build
Source-code ownership
Trusted by the brands we build for
What a production-grade transfer clone buys you.
overview
A Wise clone app is an international money transfer platform: senders quote a transfer with a transparent fee breakdown, fund it by bank, card, or local rail, and the platform converts at a locked rate and pays out to the recipient's bank, wallet, or cash pickup point. It ships as a sender app, a receiver experience, a compliance console, and an admin panel for corridors and treasury.
The purpose is running a remittance business on your own terms: your corridors, your rate markups, your compliance posture. Incumbent services price opaque spreads on high-volume corridors, and operators who show the fee breakdown up front win the customers who compare.
The engineering core is corridor architecture: funding rails and payout rails configured as pairs with their own limits and partners, a transfer state machine that handles bounced payouts as routine events, and a double-entry ledger that keeps every movement reconstructable.
Global remittance flows remain enormous in widely published World Bank and industry trackers, and mobile-first services keep taking share from legacy agents on price and speed.
Headline capabilities above the panel detail below.
Live calculator showing the fee breakdown and the offered rate against the mid-market rate before commitment.
Bank, card, and local payment rails in, with corridor-specific limits per verification tier.
The FX engine converts at the rate locked at funding, with your per-corridor markup applied and recorded.
Bank accounts, mobile wallets, and cash pickup networks, delivered through partner connectors with health monitoring.
Status visible to both parties from initiation to delivery, with receipts and references.
Bounced payouts trigger refund or re-route automatically, with the sender notified and the event on the ledger.
Receiver-side KYC and screening so every transfer is reconstructable end to end.
Per-corridor margin and volume reporting that lets you price competitively without guessing.
What these buyers share: money-movement licenses or partner rails, and corridors they understand better than the incumbents do.
Replace agent-led flows with a digital channel on the corridors you already run, with rate transparency your agents never offered.
Digitize corridors with locked conversion and payout rails, and keep the compliance console your regulators already expect.
Add a digital front door to the licenses you hold, with fraud screening and corridor analytics from day one.
Build transfer products around one or two high-volume corridors where you know the payment behavior better than anyone.
Extend payroll or invoice settlement across borders on the same rails, with batch payouts priced into your corridor economics.
$ moxace launch --nowRate transparency, payout speed, and what happens when a transfer fails. Show the fee breakdown before conversion, land funds through reliable rails, and reverse cleanly when a payout bounces.
Share your idea
a quick call, no deck required
See the live demo
every screen, admin to user
Launch with source
full code, your brand, your servers
Senders, receivers, compliance, and operations each get a real surface.
Where your customers move money.
Clarity on the delivery side.
AML operations for a money services business.
Treasury, corridors, and reconciliation.
Beyond corridor administration: the operational systems that keep a money-transfer business governable at scale.
Sender and business verification queues in one place: submission review, verification-rule enforcement, sanctions and PEP screening per transfer, and case queues with priorities and SLA tracking.
Flagged activity reviews, per-account risk profiles, policy-driven enforcement, and transaction freezes for higher-risk events, with anomaly detection feeding the queue automatically.
Real-time visibility of money movement with intervention points where rules require review, including compliance transfer holds that release only through the governance path.
Fee logic, settlements, reconciliation against partner reports, and refund handling, so treasury closes its books from platform data rather than spreadsheet archaeology.
Branding, fee structures, feature flags, and platform modes controlled centrally, with organization and team access governance and immutable admin audit logs underneath.
Integration health for KYC, payments, and messaging providers; transfer success rates and delivery performance; and revenue analytics that report per-corridor margin daily.
The transfer journey your platform runs for every corridor, end to end.
A sender enters amount and corridor, sees the fee breakdown and the offered rate against the mid-market rate before committing.
KYC checks the sender's identity, and corridor-specific limits apply per verification tier and destination rules.
The sender pays by bank, card, or local rail, and the transfer state machine moves from initiated to funded with the conversion rate locked.
The FX engine converts at the locked rate with your per-corridor markup applied, recording the conversion on the ledger.
The payout connector delivers to the beneficiary's bank account, mobile wallet, or cash pickup point, with status tracking visible to both parties.
Delivery confirmation closes the transfer with a receipt, and a bounced payout triggers the automated refund or re-route path.
Five model-driven systems working the same transfer stream. Each ships pre-tuned for remittance and sharpens as your data compounds.
Scores every transfer on sender, beneficiary, and corridor risk before funds convert, so fraud blocks before payout.
Payment signals, account history, corridor patterns, device data
Fraud caught at funding instead of recovered after payout
Forecasts payout partner success rates and corridor volatility so treasury and pricing decisions lean on evidence.
Partner settlement data, failure rates, FX volatility
Fewer bounced payouts and corridor pricing that holds margin
Surfaces structuring and velocity anomalies into case management with fewer false positives than static rules.
Transfer history, corridor norms, peer-group behavior
A screening queue your compliance team can actually clear
Ranks corridors, repeat-transfer nudges, and referral offers per sender from their transfer history.
Corridor history, frequency, beneficiary patterns
Higher transfer frequency and referral-driven growth
Pre-screens KYC document quality so clean senders onboard fast and only genuine edge cases reach the human queue.
Document images, extraction confidence, submission patterns
Faster onboarding without loosening verification standards
The modules that turn a transfer app into a full financial operations platform, each toggleable and configurable per market.
Create payment links with amount, currency, and description; send requests with due-date tracking; split shared expenses with per-participant status, all collected through your own rails.
Invoices with line items, rates, taxes, and statuses; a client directory with history and notes; PDF exports and quick re-invoicing, so individual earners run their business inside the platform.
Team invitations with role-based permissions, payroll creation and bulk execution, batch upload with scheduling, and per-item status tracking across corridors.
Virtual issuance and physical card requests against wallet balances, per-card daily and monthly limits, freeze and unfreeze, and per-card transaction history.
BTC, ETH, and USDT wallet surfaces with buy, sell, and swap flows, portfolio visibility, bridge comparison, and forward-contract support where your licensing permits.
API keys with scopes, rotation, and usage tracking; webhook delivery with test and retrigger tooling; MFA through TOTP, SMS, or email OTP with trusted-device and session management.
platform concepts
Remittance runs on corridor thinking. A corridor is a configured pair of funding rails and payout rails with its own rate markup, limits, and partner integrations, so adding a country is an adapter and a policy, not new core code. The spread between the offered rate and the mid-market rate, locked at funding, is the revenue line your FX engine applies per corridor.
The transfer state machine is the reliability concept: initiated, funded, converting, paid out, delivered, or reversed, with each state transition on the ledger. Payout bounces are expected events, not incidents, and the reversal path refunds or re-routes automatically with the sender notified. Screening runs on both sides, sender KYC at funding and beneficiary verification at payout, so every transfer your compliance console reports is reconstructable end to end.
insight
Cross-border money movement is one of the largest recurring flows in financial services. Industry trackers put global digital payment value around $37 trillion for 2026, with payments revenue near $2.5 trillion and compounding toward $3 trillion. Remittance flows into low- and middle-income countries alone run in the hundreds of billions of dollars a year, and they repeat monthly, not once.
The pricing gap is the opening. The World Bank pegs the global average cost of sending a remittance at about 6.36%, while a rate-transparent operator can serve the same corridors at a fraction of that and still hold margin. Wallets already carry roughly 30% of global point-of-sale volume and instant-payment schemes run in over 100 jurisdictions, which keeps making the digital front door cheaper to operate than the agent networks it replaces.
revenue model
The primary line is the spread between your offered rate and the mid-market rate, set per corridor and configurable in the admin panel. Fixed transfer fees, express-delivery premiums, and wallet interchange on stored balances add predictable income.
Corporate and SME cross-border payouts are the growth line: batch payments, invoice settlement, and marketplace payouts run on the same rails with higher ticket sizes. Every fee and margin parameter reports into per-corridor margin analytics, so you can price competitively without guessing.
Six monetization lines on one transfer core, quantified against regulator-published data. The figures here are modelling inputs, not projections of your platform's earnings.
| Criteria | Revenue line | How it is charged | Typical range | What sets the ceiling |
|---|---|---|---|---|
| FX spread | Markup over the interbank mid-market rate, locked at funding | 0.2% to 1.0% on major pairs, wider on thin-liquidity corridors | Competition. The World Bank's 6.36% average remittance cost means a transparent operator prices far below incumbents and still holds margin | |
| Fixed transfer fees | A per-transfer fee shown in the quote breakdown before commitment | Flat or tiered by corridor and payout speed, commonly $1 to $10 equivalent | Corridor competition and payout cost. Express premiums price against the speed your payout partner actually delivers | |
| Business subscriptions | A fixed monthly plan for payroll, bulk payouts, invoicing, and reporting tools | $10 to $100+ per business per month by module depth | Attach rate among your business customers; the only line that does not move with transfer volume | |
| Payment collections | Payment links, requests, and invoicing that pull money in through your rails | A percentage of collected value, often 1% to 3% below card-acquiring rates | Your funding-rail costs per corridor, which collections pricing must clear | |
| Card interchange | Interchange on spend from cards issued against wallet balances | EEA and UK: 0.2% debit, 0.3% consumer credit. US: 1.2% to 1.5% signature debit for small-issuer sponsors | Statute. The caps are regulator-published, and sponsor-bank size decides which side of the Durbin exemption you land on | |
| API and partner access | Programmable transfer access for platforms embedding payouts | Per-call, tiered, or negotiated platform fees | Your sponsor agreement and per-call economics; model from your quoted rate card at every volume tier |
Standard inclusions on every engagement, almost-ready or custom. Nine things you never have to ask for.
The complete unencrypted codebase transfers to you, with documentation and deployment scripts.
Your logo, colors, and store accounts across every panel, plus branded customer communications.
App store and Play Console submissions handled end to end, with production monitoring switched on.
Funding and payout rail connectors configured with locked conversion and automated split payouts.
Fraud scoring, corridor risk modeling, and AML pattern detection arrive configured for remittance, not as raw APIs.
Languages, currencies, and tax display configured for your markets during the launch window.
Containerized services on AWS or Azure with autoscaling and queue-backed intake for peak traffic.
Operational dashboards, finance reconciliation views, and CSV exports so your team starts informed on day one.
Included support window plus product updates covering bug fixes, OS compatibility, and version upgrades.
Ledger integrity and payout reliability decide the architecture.
Double-entry PostgreSQL ledger with idempotent transfer processing and an explicit state machine: initiated, funded, converting, paid out, delivered, or reversed.
Connectors for bank rails, mobile money, and cash pickup networks, with per-partner circuit breakers and automatic refund paths when payouts bounce.
Rate feeds with per-corridor markup configuration, locked conversion at funding, and hedging hooks for treasury operations.
KYC vendor integrations, sanctions screening on both sides of every transfer, React Native apps, Next.js web, and Node.js services with full audit trails.
Payout partners, KYC vendors, rate feeds, notification providers, and accounting exports ship as configured integrations, so the platform plugs into the partners your corridors already run on.
Role-based access, append-only audit logs, encrypted traffic and secrets, and rate-limited endpoints come standard, so regulator and partner due diligence has answers before it is asked.
The almost-ready AI build, day by day. Store review times can add a short buffer outside our control.
Corridors, partner rails, and rate markups locked with a written scope, and your identity applied across all four panels.
KYC vendor, funding rails, payout partners, and fee schedules configured and tested against your live partner accounts.
Pilot transfers run end to end on launch corridors: quote, fund, convert, pay out, deliver, and a full reversal-path test.
App store submissions with review buffers accounted for, production monitoring on, and full launch with post-launch support and product updates included.
Both tracks ship the same transfer core. The difference is time, price structure, and how much you want to change.
| Criteria | Almost-Ready AI Launch | Custom Build |
|---|---|---|
| Time to live | 6 working days from branding handoff | 3 to 4 weeks, scoped before work starts |
| Pricing | Fixed written quote after a short scoping call, no hourly meter | Estimated per module after the discovery call |
| Source code and IP | 100% ownership on delivery | 100% ownership on delivery |
| AI layer | Dispatch, forecasting, and personalization pre-tuned for the vertical | AI services designed around your workflows and data |
| Corridor coverage | Your launch corridors configured on proven partner adapters | Custom corridors and treasury tooling built to your partner network |
| Best for | Operators who want to launch this quarter | Teams with bespoke workflows or a unique model |
| After launch | Post-launch support and product updates included | Post-launch support and product updates included |
$ moxace launch --nowBook a walkthrough and we will demo the quote flow, payout rails, and compliance console on a live build, then send the written scope.
Share your idea
a quick call, no deck required
See the live demo
every screen, admin to user
Launch with source
full code, your brand, your servers
No two launches price the same. These are the factors that shape the written quote you receive after scoping.
The almost-ready AI build covers the proven feature set. Bespoke treasury tooling, corporate payout modules, or unique corridor logic add scoped estimate work.
Currencies, languages, and jurisdiction rules are configured per corridor. Adding corridors means more configuration, never a rebuild.
Payout partners, KYC vendors, and rate feeds are wired during the build, and each integration is estimated individually.
Out of the box, fraud scoring, corridor risk modeling, and AML pattern detection are pre-tuned for remittance. Training models on your historical transfer data is an optional, separately scoped workstream.
The core build is complete on its own. These modules add corridor depth, treasury power, or new revenue lines, from day one or as you scale.
FX forward contracts and hedge workflows for customers who need rate control and planning certainty, monetizing treasury behavior instead of just spot conversion.
Deeper review paths, stricter approval logic, and country-aware verification handling for regulated markets and compliance-heavy deployments.
BTC, ETH, and USDT wallets, bridge-aware routing, and L2 support as advanced rails where your licensing and market posture permit.
Deeper API-led integrations, webhook-driven automation, and embedded payout capabilities for platforms building on your rails.
Per-corridor rules, configurable requirements, and region-aware policies, so one codebase serves corridors with different regulatory regimes.
Advanced approval workflows, governed access layers, and operational oversight for enterprise and business deployments.
Sharable referral links, reward tracking, and incentives tied to verified activity and successful onboarding, priced against your corridor margins.
Several branded transfer platforms on one shared core, with separate branding, configuration, and operational controls per deployment.
Ready-made speed with custom-build engineering discipline.
Corridor configuration, locked conversion, and reversal paths are core product logic, not plugins fighting each other.
A ready-made launch costs a fraction of a ground-up build, with a fixed written quote before work starts.
One hundred percent of the source code transfers to you. No per-transfer royalties, no black-box dependencies.
For spend-side accounts, see our Revolut-style build and our wider fintech app development practice.
Canonical deployments from our own portfolio. Metrics are reported from live platforms, not projections.
A consumer transaction platform from the same engineering system, proving payment and matching cores hold under city-wide, real-time load.
A high-concurrency platform our engineering system ships and operates at 99.9% uptime, the same reliability bar every money platform is held to.
A high-traffic consumer platform our team ships and operates, the standard every engagement is measured against.
Identity data, transaction records, and compliance workflows make this a due-diligence product. The controls are built in, and stated plainly.
Controls aligned to OWASP ASVS and a posture mapped to PCI DSS, NIST 800-53, and ISO 27001 expectations, so partner and regulator due diligence starts from evidence, not promises. The certificates belong to your operating entity.
MFA through TOTP, SMS, or email OTP, trusted-device management, biometric login, session controls, login-history visibility, and admin session tracking across user and admin surfaces.
KYC and KYB reviews, AML/CFT case handling, suspicious-activity workflows, regulatory filing paths, and incident tracking run from the platform, with every action auditable.
Configurable data-retention policies, deletion jobs, and structured handling of sensitive operational records, so your data-protection obligations have platform support instead of manual process.
Sanctions screening on both sides of every transfer, risk scoring, flagged-transaction handling, anomaly detection, and review paths for higher-risk behavior, feeding the compliance console.
the process
Discovery maps your corridors, partners, and licensing posture, ending in a fixed written quote. Once you approve, you hand over your brand assets and we configure the platform: your identity across all four panels, your partners, rate markups, and corridor limits. The almost-ready AI build goes live in 6 working days; a custom build takes 3 to 4 weeks, planned with you up front.
You get 60 days of included support and 12 months of updates, with trained operators at handover. The first 90 days are corridor proving: watching payout partner success rates, tuning screening thresholds against real transfer patterns, and exercising the reversal path on genuine bounces. Remittance trust is won in that window, one delivered transfer at a time.
Open the web app, sign in with the printed demo credentials, or install the Android build — no signup, no sales call. What you see is what you launch.
$ moxace launch --nowBook a free consultation and get a written scope and quote.
Share your idea
a quick call, no deck required
See the live demo
every screen, admin to user
Launch with source
full code, your brand, your servers
Moxace is an independent software development company. We are not affiliated with, sponsored by, or endorsed by Wise.
The phrase “Wise clone” is used descriptively. It is how the software industry refers to building a platform with similar functionality, and how buyers search for one.
The design and codebase are built entirely by our in-house team. Nothing is taken from the Wise website, applications, or brand assets.
Wise and all third-party names and marks remain the property of their respective owners, referenced here only to describe the category of software we build.
Read the full legal notice on our disclaimer page.