Credit card bill payment
Multi-card bill detection and payment through configured rails, with reminders, autopay options, and instant confirmation on every settlement.
AI-Built CRED Clone
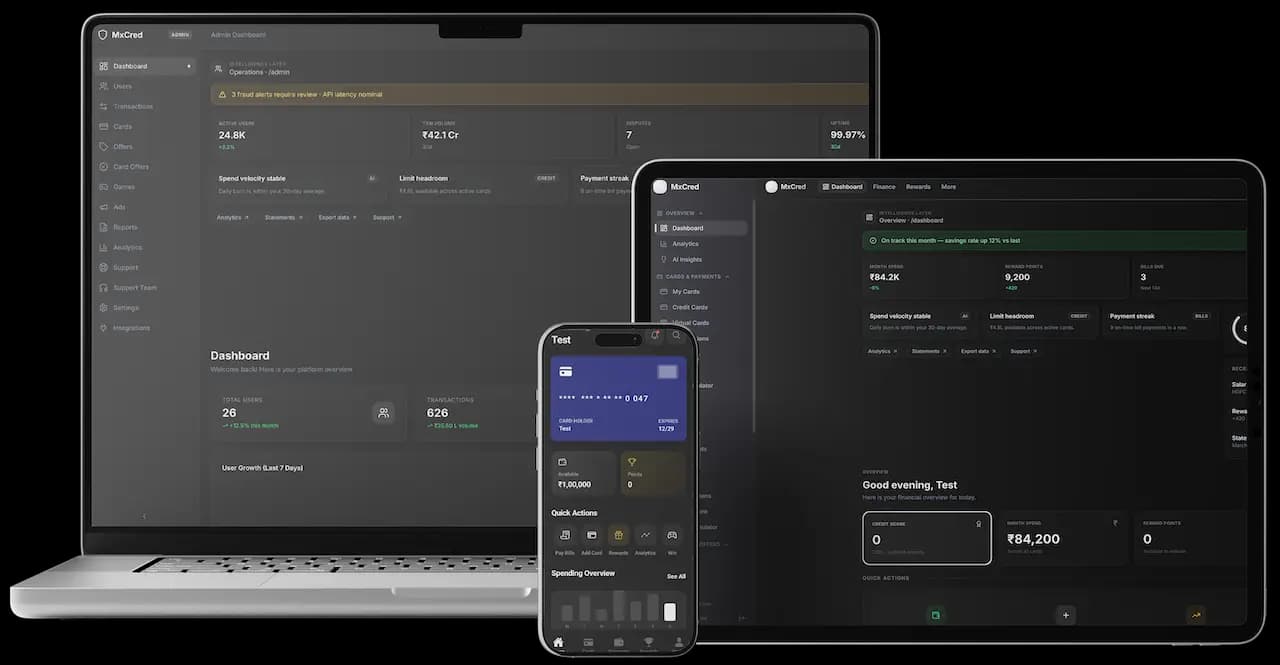
An AI-first build of the premium member-benefits pattern: effortless credit card bill payment, rewards that make paying feel like earning, and spend intelligence that gives members a reason to open the app between bills. Four synced panels ship white-label with 100% source code, owned by you from day one. The almost-ready AI build goes live in 6 working days; a custom build takes 3 to 4 weeks.
Launch-ready from
$6,999
Synced panels
Almost-ready AI launch
Custom build
Source-code ownership
Trusted by the brands we build for
Canonical facts, not promises.
overview
A CRED-style platform is a members-first fintech app centered on credit card bill payment: users pay their bills through the app, earn rewards for responsible payment behavior, and get access to premium commerce, offers, and financial products curated for a creditworthy audience.
The business problem it solves is monetizing a high-value audience without lending. The platform aggregates a segment every issuer and merchant wants, and monetizes payment rails, merchant offers, and financial-product distribution rather than credit risk, which keeps the model lighter to license than lending.
A complete build includes the member app with bill payment, rewards, and offers, the merchant and campaign side that fills the rewards catalog, an admin panel over members, tiers, and campaign economics, and integrations to card networks and bill-payment rails.
Market context, hedged: rewards-based bill payment emerged from India's card market and the pattern travels best where credit card penetration is growing and issuers compete for quality customers. We make no claims about market size, and the build is framed compliance-first: payment aggregation and product distribution are regulated activities in many markets, and licenses or partner arrangements are yours to hold.
The headline capabilities, at product level.
Multi-card bill detection and payment through configured rails, with reminders, autopay options, and instant confirmation on every settlement.
Points and perks credited on-time payments, so the least glamorous financial chore becomes the reason members open the app.
Invitation-style tiers that gate rewards, offers, and experiences, giving the membership its perceived exclusivity and your positioning its teeth.
Brand-funded discounts and experiences in a rewards catalog, with campaign economics tracked end to end from the admin panel.
Statements parsed into categories, trends, and alerts, so members get genuine insight rather than a receipt archive.
All cards in one view: limits, due dates, utilization, and payment status, refreshed automatically where the rails permit.
Offers for cards, loans, or insurance where your licenses and partnerships permit, with eligibility matching handled by the platform.
The premium, restrained interface the category is known for, applied across every panel so the brand promise is visible before a word is read.
What these buyers share: access to a creditworthy audience and the intent to monetize it without becoming a lender. If you bring the members, the platform side is the part we handle.
Where issuers fight for quality customers, a rewards aggregation layer becomes the venue they pay to reach. The AI spend core runs the insight engine.
Building a retention and engagement surface for your own cardholders under your brand, with rewards economics you control.
Turning premium-cardholder traffic into a monetizable audience with a branded app that makes offers feel earned.
Extending an existing user base into bill payment and rewards, the fastest way to add a high-trust financial touchpoint.
Deploying white-label member platforms for banks and merchants, every deployment standalone on 100% source code.
Four products operating as one system. Every panel ships in every build.
The premium surface members open daily.
Where brands fill the rewards catalog.
Run the membership from one console.
The models underneath the experience.
Four consoles, one view of members, merchants, and money.
Member and tier management with the earning rules behind them, referral program oversight, and regional settings per market.
Merchant campaign approvals with creative review, redemption tracking, campaign performance reporting, and settlement and invoicing views.
Payment rail monitoring with reconciliation views, fraud-pattern alerts on payments, and reward-liability forecasting to keep the books honest.
Distribution partner management, revenue reporting across campaigns and subscriptions, and compliance exports for regulators and partners.
The core loop from card detection to rewards, end to end.
The member adds cards through configured detection rails or statement access where permitted, and the dashboard fills automatically.
Due amounts, due dates, and utilization render in one view, with reminders scheduled before anything becomes late.
A payment initiates through the configured rail, with confirmation and receipt the moment the issuer posts the settlement.
On-time payment credits rewards automatically, with tier multipliers applied per your rules and the balance updated in place.
Members redeem on curated offers and experiences, and merchant redemptions reconcile against the campaign ledger.
Spend insights, tier progress, and referrals give the member reasons to return between bills, which is where the audience value compounds.
Five model-driven systems working the same member stream. Each ships pre-tuned for rewards fintech and sharpens as your data compounds.
Parses statements into categories, merchants, and trends, turning raw billing data into insights members actually read.
Statement data, merchant descriptors, category feedback
An app with a reason to be opened between bills
Matches members to merchant campaigns and financial products by spend profile and tier, so offers convert instead of annoying.
Spend patterns, tier, redemption history, campaign rules
Merchant campaigns that perform, which keeps brands paying
Watches bill payments for account takeover, stolen-card funding, and abuse patterns before settlements complete.
Payment sources, device signals, velocity patterns
Payment rails protected before losses, not after
Projects reward liability from earning and redemption behavior, so your balance sheet never gets surprised by your own loyalty program.
Earning curves, redemption rates, campaign calendars
Loyalty economics managed by forecast, not by quarterly shock
Detects members going quiet and surfaces which win-back offers and tier benefits will bring them back.
Login cadence, payment frequency, offer engagement
Retention actions timed to the member, not the calendar
platform concepts
The first concept is the member ladder. Tiers gate rewards, offers, and experiences, and earning behavior moves members up, so the platform's most valuable feature is status that feels earned. Because tiers and multipliers are admin-configurable, you can run the exclusivity dial per market without engineering cycles.
The second is campaign economics. Merchants fund the catalog because the audience is worth reaching, redemptions reconcile against campaign ledgers, and AI performance reporting keeps the renewal conversation honest. The rewards catalog is therefore a two-sided marketplace in miniature, and the platform sits in the middle of it.
The third is the payment rail perimeter. Bill payments run through configured, regulated rails with reconciliation and settlement views, and financial product distribution activates only where your licenses and partnerships permit. The platform enforces process and auditability; the regulated relationships are yours to hold.
Merchant campaign fees: brands pay to reach a curated, creditworthy audience, and campaign performance data keeps them paying.
Interchange and rail revenue on bill payments, where your rail agreements provide it.
Financial product distribution commissions for card, loan, or insurance offers where licenses permit.
Premium subscription tiers with richer rewards, experiences, and priority support.
Every rate and rule lives in the admin panel, so you can reprice campaigns and tiers without a code release.
Four groups, each mapped to the part of the rewards promise it protects.
Tiers gating rewards, offers, and experiences with earning behavior moving members up, so the platform's most valuable feature is status that feels earned, and the exclusivity dial configures per market without engineering cycles.
Statements parsed into categories, trends, and alerts with payment behavior scoring, so members get genuine insight rather than a receipt archive, and utilization and due-date tracking arrive before anything becomes late.
Merchants funding the catalog because the audience is worth reaching, redemptions reconciling against campaign ledgers, and AI performance reporting keeping the renewal conversation honest.
Bill payments through configured, regulated rails with reconciliation and settlement views, autopay and reminders, fraud-pattern alerts on payments, and distribution activating only where your licenses permit.
insight
Credit card rewards and loyalty platforms keep compounding past the hundred-billion-dollar mark globally by 2030 on widely published forecasts, with premium cardholder audiences the segment merchants pay most to reach and engagement platforms the venue where that reach gets sold.
The engineering wedge is the two-sided loop: a member base worth reaching and campaign economics that reconcile honestly are what keep merchants renewing, and a member ladder that makes status feel earned is what keeps members opening daily. The revenue table below quantifies the lines.
Six monetization lines across the platform, quantified against published industry benchmarks. Every rate is admin-configurable; the figures here are modelling inputs, not projections of your platform's earnings.
| Criteria | Revenue line | How it is charged | Typical range | What sets the ceiling |
|---|---|---|---|---|
| Merchant campaigns | Brands pay to reach the member base | Campaigns commonly $5,000 to $500,000+ per campaign | Audience quality. Campaigns renew while performance data stays honest | |
| Interchange and rails | Revenue on bill payments where agreements provide | Rail revenue commonly 0.5% to 2% of payment volume | Payment volume. Rails earn while the bill flow stays daily | |
| Distribution commissions | Card, loan, insurance offers where licensed | Commissions commonly $20 to $300+ per funded account | License scope. Distribution earns where regulation permits | |
| Premium subscriptions | Richer rewards, experiences, priority support | Subs commonly $5 to $50+ per month | Member depth. Subs earn while status stays worth it | |
| Rewards liability margin | Economics on points issuance and redemption | Breakage commonly 10% to 30% of liability | Liability honesty. Margin earns while forecasting stays accurate | |
| White-label deployments | Branded member platforms for banks | Deployments commonly $50,000 to $500,000+ | Institution demand. Deals close while the ladder stays configurable |
Standard inclusions on every engagement, almost-ready or custom. Nine things you never have to ask for.
The complete unencrypted codebase transfers to you, with documentation and deployment scripts.
Your logo, colors, and store accounts across all four panels, plus branded member communications.
App store and Play Console submissions handled end to end, with production monitoring switched on.
Bill-payment rails and Stripe, PayPal, and regional gateways configured, with settlement and reconciliation views.
Spend intelligence, offer matching, and fraud detection arrive configured for rewards fintech, not as raw APIs.
Languages, currencies, and regional settings configured for your markets during the launch window.
Containerized services with queue-backed payment processing and autoscaling for campaign-day spikes.
Rewards liability, campaign, and payment dashboards plus CSV exports so your team starts informed on day one.
Included support window plus product updates covering bug fixes, OS compatibility, and version upgrades.
Payment integrity is the product. We engineer it that way.
Bill payments through configured rails with idempotent processing, settlement reconciliation, and instant member confirmation, so a retried payment can never double-charge.
Points earning, tiering, and redemption as a governed ledger with liability reporting, so the loyalty program stays auditable as it scales.
A parsing and categorization pipeline with member-facing insights, built with privacy-safe aggregation rather than raw data exposure.
Containerized services on AWS or GCP with autoscaling. See how this fits our wider fintech app development practice.
Card networks, bill-payment rails, merchant systems, and identity vendors ship as configured integrations, so the platform plugs into the financial stack your market already runs.
Role-based access, append-only audit logs, encrypted traffic and secrets, and data-residency controls come standard, so the compliance story survives due diligence.
The almost-ready AI build, day by day. Rail and partner onboarding run on their own timelines outside this window.
Member tiers, rewards rules, and rail scope locked with a written scope, and your identity applied across all four panels.
Payment rails, card networks, and merchant systems configured and tested against your live accounts.
Merchant campaigns loaded, seed members onboarded, and live test flows run end to end: card detection, payment, rewards, redemption.
App store submissions with review buffers accounted for, production monitoring on, and full launch with post-launch support included.
Both tracks ship the same payment core. The difference is time, price structure, and how much you want to change.
| Criteria | Almost-Ready AI Launch | Custom Build |
|---|---|---|
| Time to live | 6 working days from branding handoff | 3 to 4 weeks, scoped before work starts |
| Pricing | Fixed written quote after a short scoping call, no hourly meter | Estimated per module after the discovery call |
| Source code and IP | 100% ownership on delivery | 100% ownership on delivery |
| AI layer | Spend intelligence, matching, and fraud models pre-tuned | AI services designed around your members and data |
| Rewards model | Points, tiers, and campaign catalog ready to configure | Any loyalty model, built to your commercial spec |
| Rails | Standard bill-payment integrations wired | Rail strategy designed around your agreements |
| Best for | Operators who want to launch this quarter | Teams with bespoke partnerships or regimes |
$ moxace launch --nowBook a walkthrough and we will demo bill payment, rewards, and the merchant portal on a live build, then send the written scope.
Share your idea
a quick call, no deck required
See the live demo
every screen, admin to user
Launch with source
full code, your brand, your servers
No two launches price the same. These are the factors that shape the written quote you receive after scoping.
The almost-ready AI build covers the proven feature set. Bespoke loyalty mechanics or lending-adjacent modules add scoped estimate work.
Payment rails, currencies, and rewards rules are configured per market. Adding markets means more configuration, never a rebuild.
Card networks, rails, and merchant systems are wired during the build, and each integration is estimated individually.
Out of the box, models are pre-tuned for rewards fintech. Training on your member data is an optional, separately scoped workstream.
Extend the CRED-style build once the core member loop is running.
A cashback wallet with earning and redemption rules, the instant-gratification layer on top of tiered status.
Curated experiences and event access as rewards, the differentiation that keeps premium tiers premium.
Credit score tracking with improvement guidance where rails permit, the engagement feature that opens daily.
Rent and utility payments through configured rails, expanding the payment volume that carries rail revenue.
Deeper campaign analytics with audience cohorts and lift measurement, the reporting that renews merchant spend.
Deploy the platform for banks and merchant networks under their own identity, with per-tenant tiers and campaign configuration.
Premium member experience with payment-grade engineering.
The restrained, premium interface the category is known for, applied across every panel, because the design is the positioning.
Idempotent payments, reconciliation, and rewards as a governed ledger, so the loyalty program never becomes a liability surprise.
One hundred percent of the source code transfers to you. No per-member royalties, no black-box dependencies.
Pair with our fintech app development practice to extend into lending-adjacent products on the same system.
Canonical deployments from our own portfolio. Metrics are reported from live platforms, not projections.
A high-traffic consumer platform our team ships and operates at national-carrier scale, the same bar every build is held to.
A consumer platform from the same engineering system, proving the infrastructure core holds under real-time load with strict uptime demands.
A high-volume consumer experience our team ships at global-release scale, the same discipline applied to every launch.
Tap a card to see how the platform defends its members.
Tiers gate rewards and experiences and earning behavior moves members up, with tiers and multipliers admin-configurable, so exclusivity is a dial rather than a promise.
The parsing pipeline turns statements into categories, trends, and alerts with behavior scoring, so members get genuine insight instead of a receipt archive.
Redemptions reconcile against campaign ledgers with AI performance reporting, so the merchant renewal conversation starts from data, not anecdotes.
Bill payments run through configured, regulated rails with reconciliation and settlement views, and fraud-pattern alerts watch every payment.
Financial product offers activate only where your licenses and partnerships permit, with eligibility matching enforced by the platform.
Member-level data powers the models while reporting to merchants and partners stays aggregated, so insight never becomes exposure.
the process
The engagement starts with a discovery call and ends with a written scope and quote before any work begins. On the almost-ready AI path you hand over branding assets and partner agreements, we apply your identity across every panel, configure tiers, rewards, and rails, and go live in 6 working days. Custom modules are scoped as sprints and quoted in writing first, so there are no surprise invoices.
After launch you have post-launch support and product updates included. Expect the first 90 days to be about catalog and habit: signing the anchor merchants that fill the rewards page, watching the first payment cycles reconcile cleanly, and tuning tier economics from real earning data. The software handles payments, rewards, and intelligence; the members and the merchant relationships are what make it a business.
Open the web app, sign in with the printed demo credentials, or install the Android build — no signup, no sales call. What you see is what you launch.
$ moxace launch --nowBook a free consultation and get a written scope and price.
Share your idea
a quick call, no deck required
See the live demo
every screen, admin to user
Launch with source
full code, your brand, your servers
Moxace is an independent software development company. We are not affiliated with, sponsored by, or endorsed by CRED.
The phrase “CRED clone” is used descriptively. It is how the software industry refers to building a platform with similar functionality, and how buyers search for one.
The design and codebase are built entirely by our in-house team. Nothing is taken from the CRED website, applications, or brand assets.
CRED and all third-party names and marks remain the property of their respective owners, referenced here only to describe the category of software we build.
Read the full legal notice on our disclaimer page.