Double-entry ledger core
Every movement posts as balanced entries with immutable audit history, so balances reconcile by construction rather than by nightly batch fixes.
AI-Built Banking Script
An AI-first build of a complete digital banking suite: double-entry ledger integrity, card issuing and controls, tiered KYC that scales limits honestly, and fraud scoring that watches every transaction stream. Four synced panels ship white-label with 100% source code, owned by you from day one. The almost-ready AI build goes live in 6 working days; a custom build takes 3 to 4 weeks.
Launch-ready from
$3,699
Synced panels
Almost-ready AI launch
Custom build
Source-code ownership
Trusted by the brands we build for
Canonical facts, not promises.
overview
A core banking script is the software skeleton of a digital bank: customer accounts with a real double-entry ledger, card issuing and transaction controls, deposits and transfers through licensed rails, tiered KYC with limits that follow verification level, and the admin console where an operator runs the whole institution.
Its purpose is institutional, not cosmetic. Banks are regulated businesses that monetize deposits, interchange, fees, and credit, and the script exists so a licensed operator, an NEoBI-leaning startup working with a BaaS partner, or an incumbent digitizing a book can run those mechanics on software they own rather than rent per account.
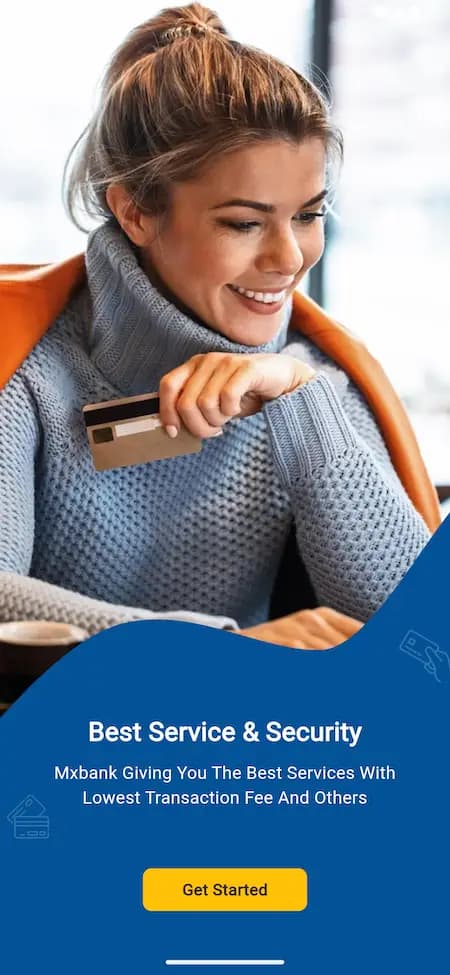
The platform ships as a customer banking app for iOS, Android, and web, an operations console for compliance and support teams, a finance and treasury view over balances and settlements, and the transaction core with ledger, limits, and integrations to card issuers and banking partners.
Market context, hedged: digital banking demand is structural, but this is a licensed activity everywhere. We make no claims about market size, and every build is framed compliance-first: the software enforces the process, while the licenses, the sponsor bank relationships, and the regulatory obligations are yours to hold per market.
The headline capabilities, at product level.
Every movement posts as balanced entries with immutable audit history, so balances reconcile by construction rather than by nightly batch fixes.
Customer accounts, internal transfers, and outbound payments through configured rails, with limits and cutoffs enforced server-side.
Virtual and physical cards via issuer integrations, with per-card freezes, merchant categories, and geographic controls the customer manages in-app.
Verification levels that gate deposit, transaction, and balance limits, wired into the flow so funds cannot move around the checks.
Real-time scoring on every transaction from device, velocity, merchant, and behavioral signals, holding suspect payments for review instead of after the loss.
Configurable savings pockets, goal accounts, and interest accrual rules you can launch per market without a code release.
KYC review queues, transaction monitoring, sanctions-screening hooks, and audit exports that regulators and partners can actually read.
Account information and payment initiation hooks where regulations permit, so your platform plugs into the wider financial grid.
What these buyers share: a regulatory path they are pursuing and the need to own the software that runs the institution. If you bring the license or partner bank, the platform side is the part we handle.
Launching under a sponsor bank's umbrella. The ledger and compliance core runs the hard part while you build the customer brand.
Replacing a legacy front end with a modern suite on infrastructure your own team can audit, extend, and own outright.
Digital-first deposit and payment products for member bases, with tiered KYC matching your existing onboarding discipline.
Running internal banks for ecosystems: marketplaces, franchises, or groups that need accounts and controls under their own roof.
Delivering branded banking suites to licensed clients, every deployment a standalone institution on 100% source code.
Four products operating as one system. Every panel ships in every build.
Where customers live with their money.
For compliance and support teams.
Where the institution watches its books.
The engine underneath everything.
Four consoles, one view of compliance, money, and risk.
The KYC review queue with tier approvals, sanctions screening hooks, AI-prioritized transaction review, and a full audit trail across every operator action.
Customer support tooling, dispute and chargeback intake, card lifecycle management, and role-based operator permissions with recovery and replay tooling.
Real-time balance sheets, settlement and reconciliation views, interest accrual reports, float and liquidity views, and cutoff and holiday calendars.
Fee revenue dashboards, rate and limit configuration per tier and market, CSV and partner exports, and webhook event stream monitoring.
The journey of a payment, from request to reconciled ledger.
The customer signs in with biometrics or two-factor, and the session carries device and permission context into every request.
They enter a transfer or card payment; limits, balances, and KYC tier are checked server-side before anything moves.
The AI scoring model reads velocity, merchant, device, and behavioral signals in real time and approves, holds, or declines.
The payment posts as balanced double entries with an idempotency key, so a retry can never double-send.
The payment reaches the configured rail or issuer, and settlement confirmations reconcile back against the ledger entry.
The customer sees the movement instantly, the operations console logs every hop, and the audit trail is export-ready for regulators.
Five model-driven systems working the same transaction stream. Each ships pre-tuned for banking workloads and sharpens as your data compounds.
Scores every transaction in real time from device, velocity, merchant, and behavioral signals, holding the suspect before funds move.
Transaction stream, device signals, merchant data, velocity patterns
Fraud intercepted at authorization instead of discovered in chargebacks
Flags structuring, unusual corridors, and AML-relevant patterns for your compliance team with evidence attached.
Ledger entries, counterparty graphs, KYC tiers, corridor norms
AML review that starts from a ranked queue, not a blank list
Scores customer cash-flow behavior to drive savings nudges, limit increases, and credit product eligibility where you offer them.
Balance history, inflow regularity, product usage
Risk-based limits instead of one blunt tier for everyone
Classifies inbound support and dispute messages, summarizes account context, and routes the sensitive cases to humans first.
Support threads, transaction history, product state
Faster resolution and support costs that scale sublinearly
Detects disengaging customers early so retention and cross-sell reach them while the relationship is live.
Login cadence, product adoption, transaction frequency
Retention actions timed before the customer has mentally left
platform concepts
The first concept is ledger integrity. Money never appears or disappears; every movement posts as balanced double entries with an immutable audit trail, and idempotency keys make network retries harmless. That discipline is what lets a regulator, an auditor, or your own finance team reconcile the books without a spreadsheet investigation.
The second is tiered trust economics. KYC levels gate limits rather than features entirely, so a customer can onboard in minutes and unlock capacity as they verify, while the compliance surface grows with exposure. Fees, interest rates, and product terms attach per tier and per market, which is what keeps the commercial model legible as you expand.
The third is the integration perimeter. Issuers, BaaS partners, sanctions screening, and payment rails live at defined, documented boundaries with idempotent contracts and reconciliation views. That structure is what lets you swap a partner or add a rail without the migration becoming a rewrite.
Interchange revenue on card spend, the workhorse of modern digital banking economics.
Account and service fees: monthly plans, premium tiers, and per-transfer pricing where your market accepts them.
Interest margin on savings products and float, configured per market and product.
Credit products where your license permits, priced by the risk models rather than flat rates.
Every rate and limit lives in the admin console, so you can reprice per market without a code release.
Four groups, each mapped to the part of the banking promise it protects.
Every movement posts as balanced double entries with an immutable audit trail and idempotency keys making retries harmless, so a regulator, auditor, or your finance team reconciles without spreadsheet archaeology.
KYC levels gate capacity rather than features entirely, with document and liveness verification, velocity and amount limits enforced server-side, and the compliance surface growing with exposure.
Card lifecycle management with customer controls, interchange-bearing spend, instant internal transfers, scheduled and multi-currency payments, and AI fraud scoring reading velocity, merchant, device, and behavioral signals.
Issuers, BaaS partners, sanctions screening, and payment rails at defined, documented boundaries with idempotent contracts and reconciliation views, so swapping a partner never becomes a rewrite.
insight
Digital banking keeps compounding toward the trillion-dollar mark in global revenue by 2030 on widely published forecasts, with neobanks reaching sustained profitability on interchange, float, and fee stacks rather than growth-at-all-costs acquisition. The category's unit economics reward operators who own their ledger.
The engineering wedge is reconciliation discipline: books that close without spreadsheet investigation and partner swaps that stay at defined boundaries are what licensed operators actually buy. The revenue table below quantifies the lines.
Six monetization lines across the platform, quantified against published industry benchmarks. Every rate is admin-configurable; the figures here are modelling inputs, not projections of your platform's earnings.
| Criteria | Revenue line | How it is charged | Typical range | What sets the ceiling |
|---|---|---|---|---|
| Interchange | Per-transaction revenue on card spend | Interchange commonly 0.2% to 2% of spend | Active spend. Revenue scales while cards stay top-of-wallet | |
| Account and service fees | Monthly plans, premium tiers, per-transfer pricing | Fees commonly $1 to $20+ per month per account | Perceived value. Fees hold while the app earns its keep | |
| Interest margin | Margin on savings products and float | Margins commonly 1% to 5% on deposits | Deposit growth. Margin scales while trust holds | |
| Credit products | Lending where your license permits | Spreads commonly 5% to 25%+ by risk tier | Risk models. Credit earns while underwriting stays honest | |
| Premium subscriptions | Paid tiers with richer features and limits | Subs commonly $5 to $25+ per month | Feature depth. Subs earn while perks stay worth it | |
| White-label deployments | Branded cores for regional banks and fintechs | Deployments commonly $50,000 to $500,000+ | BaaS demand. Deals close while integration stays cheap |
Standard inclusions on every engagement, almost-ready or custom. Nine things you never have to ask for.
The complete unencrypted codebase transfers to you, with documentation and deployment scripts.
Your logo, colors, and store accounts across all four panels, plus branded customer communications.
App store and Play Console submissions handled end to end, with production monitoring switched on.
Card issuers, BaaS partners, and payment rails configured per your sponsor agreements, with reconciliation views.
Fraud scoring, monitoring, and triage arrive configured for banking workloads, not as raw APIs.
Languages, currencies, and regional settings configured for your markets during the launch window.
Containerized services with encrypted secrets, redundant deployments, and disaster-recovery configurations.
Ledger, compliance, and revenue dashboards plus regulator-ready exports so your team starts informed on day one.
Included support window plus product updates covering bug fixes, OS compatibility, and version upgrades.
Ledger integrity is the product. We engineer it that way.
Double-entry posting, idempotent processing, and immutable audit history, so the books reconcile by construction and retries never double-send.
Encryption at rest and in transit, hardware-backed customer authentication, role-based operator access, and rate-limited APIs as the floor, not the feature list.
Tiered KYC, sanctions-screening hooks, AML monitoring queues, and export-ready audit trails that regulators and sponsor banks can actually review.
Containerized services with redundant deployment and recovery tooling. See how this fits our wider fintech app development practice.
Card issuers, BaaS providers, sanctions screening, identity vendors, and notification services ship as configured integrations, so the platform plugs into the institutional stack you already run.
Settlement files reconcile against ledger entries automatically, with break views and exports, so finance closes the books without manual matching.
The almost-ready AI build, day by day. Regulatory approval timelines are yours and sit outside this window.
Products, limits, KYC tiers, and rail scope locked with a written scope, and your identity applied across all four panels.
Issuer, BaaS, screening, and notification integrations configured and tested against your live partner accounts.
Accounts, cards, and savings products configured, and a pilot cohort runs real flows end to end: onboarding, transfer, card spend, statement.
App store submissions with review buffers accounted for, production monitoring on, and full launch with post-launch support included.
Both tracks ship the same ledger core. The difference is time, price structure, and how much you want to change.
| Criteria | Almost-Ready AI Launch | Custom Build |
|---|---|---|
| Time to live | 6 working days from branding handoff | 3 to 4 weeks, scoped before work starts |
| Pricing | Fixed written quote after a short scoping call, no hourly meter | Estimated per module after the discovery call |
| Source code and IP | 100% ownership on delivery | 100% ownership on delivery |
| AI layer | Fraud scoring, monitoring, and triage pre-tuned for banking | AI services designed around your products and data |
| Ledger and compliance | Double-entry ledger and KYC tiers pre-configured | Policy engine designed around your regulatory regime |
| Rails and partners | Standard issuer and BaaS integrations wired | Any rail or partner, integrated to your agreements |
| Best for | Operators who want to launch this quarter | Institutions with bespoke products or regimes |
$ moxace launch --nowBook a walkthrough and we will demo the ledger, compliance console, and customer app on a live build, then send the written scope.
Share your idea
a quick call, no deck required
See the live demo
every screen, admin to user
Launch with source
full code, your brand, your servers
No two launches price the same. These are the factors that shape the written quote you receive after scoping.
The almost-ready AI build covers the proven feature set. Bespoke credit products or unique policy engines add scoped estimate work.
KYC tiers, limits, and product terms are configured per market and license. Adding regimes means more configuration, never a rebuild.
Issuers, BaaS partners, screening vendors, and rails are wired during the build, and each integration is estimated individually.
Out of the box, fraud and monitoring models are pre-tuned for banking. Training on your historical transaction data is an optional, separately scoped workstream.
Extend the banking build once the core ledger loop is running.
Loan origination with risk-model pricing and repayment scheduling, where your license permits, the margin-rich line of banking.
Round-ups, automated saving rules, and goal tracking with interest accrual, the engagement feature that grows deposits.
Foreign-currency balances with conversion pricing, capturing travelers and remittance users profitably.
Business accounts with approval flows, bulk payments, and spend cards, anchoring higher-balance relationships.
Personalized spending insights and cash-flow forecasting, the daily-open driver that keeps the app installed.
Deploy the core for regional banks and fintechs under their own identity, with per-tenant rails and fee configuration.
Fintech speed with bank-grade ledger discipline.
Double-entry integrity, idempotency, and reconciliation are the core, because a bank whose books do not reconcile has nothing.
KYC tiers, AML queues, and audit exports ship built in. Licenses are yours to hold; the software enforces the process.
One hundred percent of the source code transfers to you. No per-account royalties, no black-box dependencies in a regulated stack.
Pair with our fintech app development practice or extend into payments with the same engineering system.
Canonical deployments from our own portfolio. Metrics are reported from live platforms, not projections.
A high-traffic consumer platform our team ships and operates at national-carrier scale, the same bar every build is held to.
A consumer platform from the same engineering system, proving the infrastructure core holds under real-time load with strict uptime demands.
A high-volume consumer experience our team ships at global-release scale, the same discipline applied to every launch.
Tap a card to see how the platform defends its books.
Every movement posts as balanced double entries with an immutable audit trail, so the books reconcile without a spreadsheet investigation.
Idempotency keys make network retries harmless, so a dropped connection at the wrong moment can never post a payment twice.
KYC tiers gate capacity rather than features entirely, with velocity and amount limits checked server-side before anything moves.
AI scoring reads velocity, merchant, device, and behavioral signals in real time and approves, holds, or declines, with the review queue prioritized for humans.
Role-based operator permissions and a full audit trail mean compliance questions meet evidence, not reconstruction.
Issuers, BaaS partners, and rails live at defined, documented boundaries with idempotent contracts, so swapping a partner never becomes a rewrite.
the process
The engagement starts with a discovery call and ends with a written scope and quote before any work begins. On the almost-ready AI path you hand over branding assets and your partner agreements, we apply your identity across every panel, configure KYC tiers, products, and integrations, and go live in 6 working days. Custom modules are scoped as sprints and quoted in writing first, so there are no surprise invoices.
After launch you have post-launch support and product updates included. Expect the first 90 days to be about operations, not code: clearing the first KYC queues efficiently, tuning fraud thresholds against real traffic, and closing the first reconciliation cycles cleanly. The engineering handles integrity and auditability; the license, the partners, and the operating discipline are what turn the platform into a bank.
Open the web app, sign in with the printed demo credentials, or install the Android build — no signup, no sales call. What you see is what you launch.
Branch: https://mxbank.mimeld.com/admin
Admin: https://mxbank.mimeld.com/admin
$ moxace launch --nowBook a free consultation and get a written scope and price.
Share your idea
a quick call, no deck required
See the live demo
every screen, admin to user
Launch with source
full code, your brand, your servers
All product names, trademarks, and brands referenced are the property of their respective owners, used for identification purposes only. Read the full legal notice on our disclaimer page.